A newly completed ground-oriented Vancouver fourplex multiplex on a standard residential lot, valued by appraisers primarily on the income it produces rather than nearby house sales
Investment

Why Your Multiplex Appraises Lower Than You Expect

8 min read

The building is finished, the units are rented, and the bank's appraisal comes back lower than expected. In a soft market that gap can be several percent, and it lands as cash you have to find. Multiplex appraisal runs on income, not on the house next door. Understand it going in and you can design around it.

Key takeaway

An investor and builder guide to why a completed rental multiplex often appraises below expectation.

Explains the three approaches appraisers use (sales comparison, income approach as net operating income divided by a cap rate, and cost approach as land plus build cost minus depreciation), and why the income approach is typically primary for stabilized income-producing property, with sales comparison as a secondary check. Uses Urban Land Institute data from April 2026 that multifamily construction costs are more than 30% above levels five years ago to explain the cost approach and the development spread (when existing comparable buildings trade well below replacement cost, ground-up development becomes financially irrational). Notes appraisals can come back significantly below purchase price and that in a strongly appreciating market a gap of 3% to 8% should be budgeted for, that a low appraisal is a financing problem because lenders size loans off appraised value, and that builders can design for the appraisal by getting rents, unit mix, and build cost right at the lot-selection stage.

What this covers

  • the three approaches to value and which one leads for multiplex
  • why the income approach rules a finished rental multiplex
  • the cost approach and the rising build-vs-value spread
  • how a low appraisal shrinks your loan and demands cash
  • designing for the appraisal at the lot-selection stage
multiplex appraisal valuation income-approach financing vancouver

Here is a moment that catches a lot of first-time multiplex builders off guard. The building is finished, the units are rented, and then the bank’s appraisal comes back lower than expected. The gap between what you thought it was worth and what the appraiser wrote down is not a rounding error. In a soft market it can be several percent of the value, and it lands as cash you have to find.

Multiplex appraisal does not work the way a house appraisal works. If you understand that going in, you can design and underwrite around it instead of getting surprised at the finish line.

Three ways to value the same building

Every appraiser has three tools. The sales comparison approach looks at recent sales of similar properties and adjusts for differences. The income approach takes the net operating income the building produces and divides it by a market cap rate to get a value. The cost approach adds land value to the cost of rebuilding the structure, then subtracts depreciation.

For a single-family house, the sales comparison approach dominates because there are lots of similar houses selling nearby. For a completed rental multiplex, the picture flips. Market participants price these buildings on the income they throw off, so the income approach usually leads, and sales comparison acts as a check. That single difference is why homeowners who think in “price per house on my street” terms get surprised.
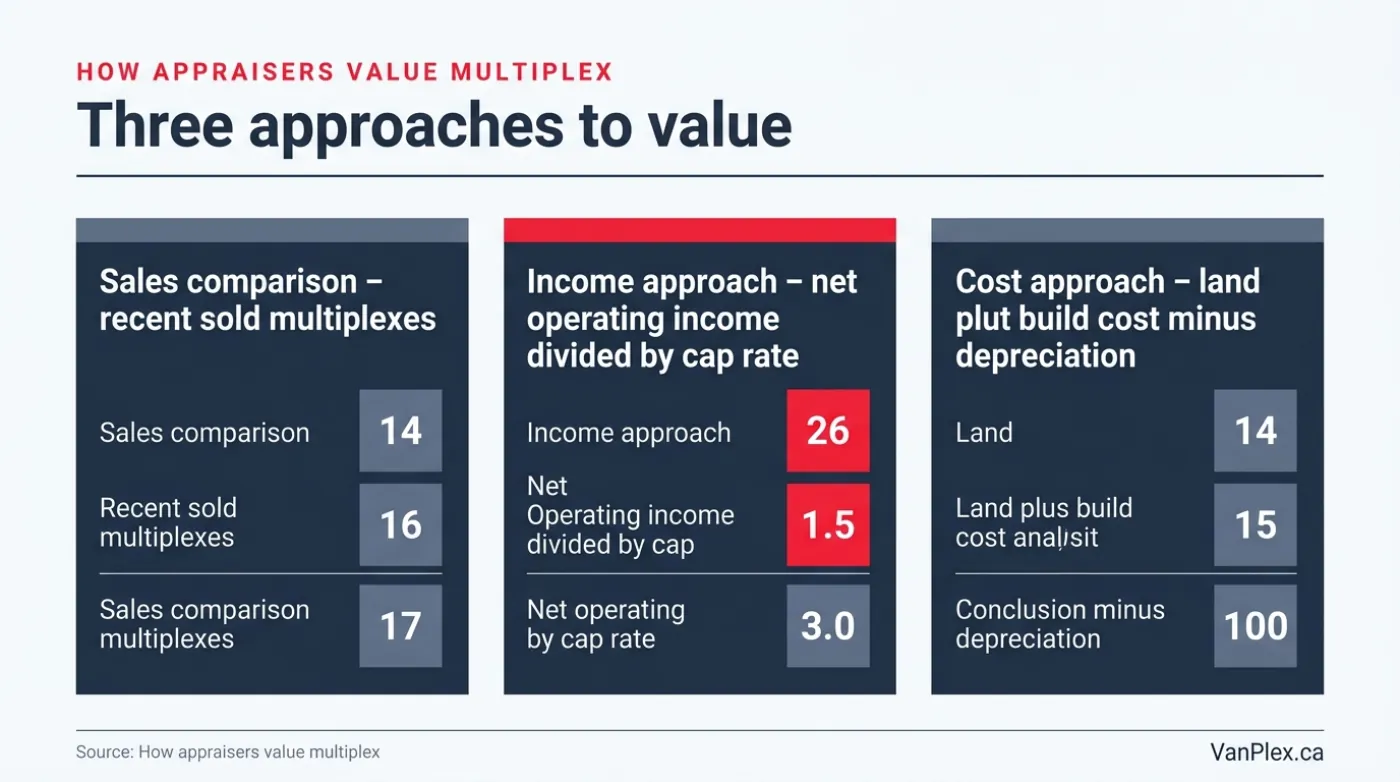
Three filled panels explaining the sales comparison, income, and cost approaches appraisers use to value a multiplex, with the income approach highlighted as primary

Why the income approach rules a finished multiplex

Think about what a buyer of a fourplex is actually buying. They are buying the rent roll. So the appraiser follows the same logic. Add up the gross rents, subtract vacancy and operating costs to get net operating income, then divide by a cap rate that reflects what similar buildings trade at.

The math is unforgiving in one direction. If your rents come in below what you projected, or your operating costs run high, your net operating income drops, and the value drops with it. A small miss on monthly rent per unit gets multiplied across every unit and then divided by a small cap rate, which magnifies it. This is why rent assumptions are not a detail. They are the value.

The cost approach and the “why build” question

The cost approach matters most for new construction, and right now it carries a warning. Multifamily construction costs are more than 30% above where they sat five years ago. When it costs far more to build than to buy an existing comparable building, ground-up development starts to look irrational on paper.

A simple example makes it concrete. If a builder can buy a functionally similar existing building for a certain price per square foot, and it costs meaningfully more per square foot to build one new, the development spread does not support construction. The gap between build cost and finished value is the whole game. A well-chosen lot with strong rents and a controlled build closes that gap. A weak lot with soft rents and cost overruns leaves it open, and the appraisal shows it.
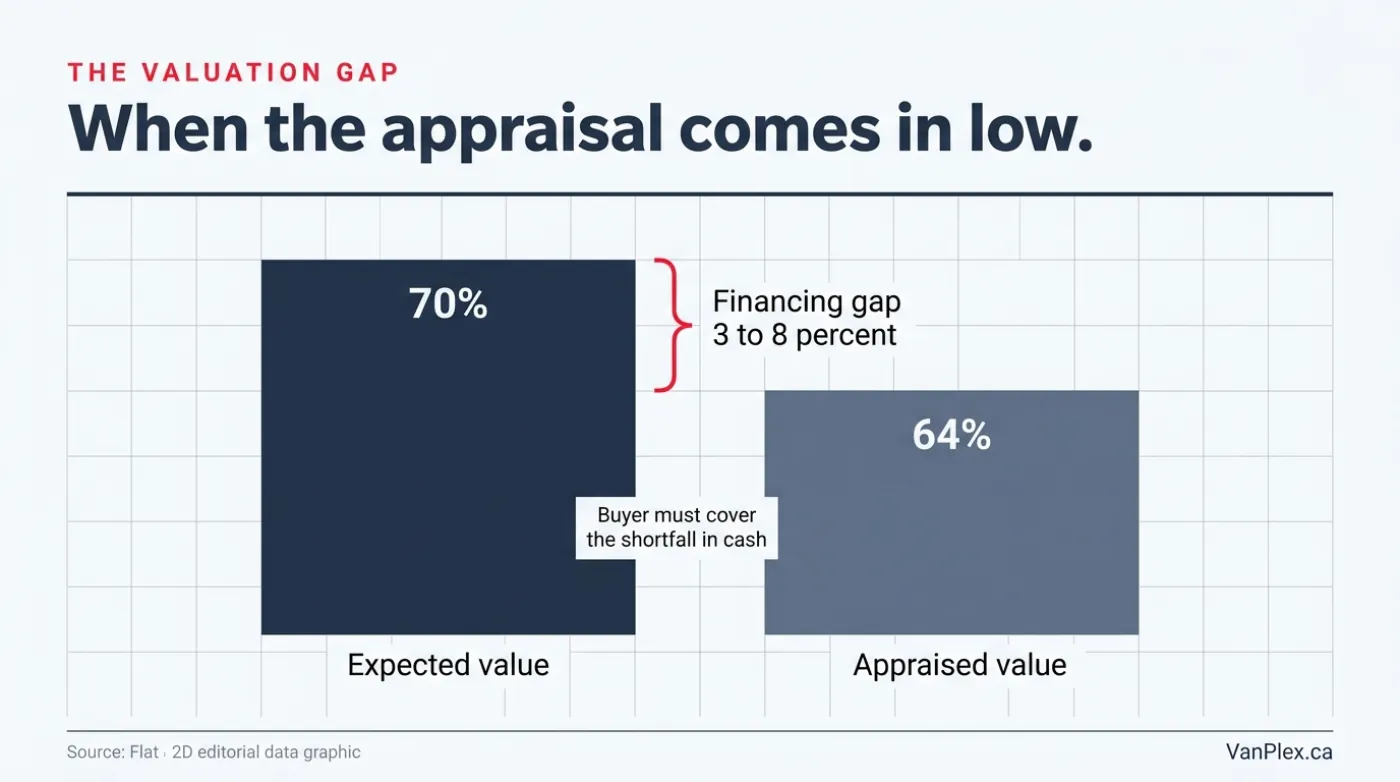
A two-bar comparison showing an expected value taller than the appraised value, with a red bracket labeling the financing gap of 3 to 8 percent that the buyer must cover in cash

What a low appraisal does to your loan

Here is the part that turns a number into a real problem. Your lender does not size your mortgage off what you paid or what you spent to build. It sizes it off the appraised value, up to whatever loan-to-value ratio your program allows. If the appraisal comes in low, the loan comes in low, and you have to cover the difference in cash.

Appraisals can come back significantly below the purchase price, and sellers get caught off guard when they assume their assessed value supports their asking price. The same trap catches builders who assume their cost supports the value. If you are counting on the finished appraisal to refinance out your construction loan, a shortfall can leave you short at exactly the wrong moment.

How to design for the appraisal, not against it

You have more control than you think, because you build the inputs the appraiser will use. Get the rents right by checking real market rents for your unit sizes, not hopeful numbers. Choose a unit mix that the market actually pays for. Control the build so your cost does not swallow the value. And pick a lot where the land basis leaves room between cost and finished value.

None of this happens at the appraisal stage. It happens at the lot selection and design stage, months earlier. The builders who never get a nasty surprise are the ones who underwrote the income approach before they broke ground, not after.

Common questions about multiplex appraisals

Why did my multiplex appraise lower than my single-family neighbour’s house? Different method. Your neighbour’s house is valued on comparable house sales. Your completed rental multiplex is valued mostly on the income it produces. If the income is soft, the value is soft, regardless of what houses sell for.

Can I challenge a low appraisal? Sometimes. If the appraiser used weak comparables or missed real rent data, you can provide better evidence. But you cannot argue away a genuine income shortfall. Fixing the number usually means fixing the rents or the cost, which is hard after the fact.

Does BC Assessment value equal appraised value? No. BC Assessment is a mass-appraisal figure for property tax. A lender’s appraisal is a specific market valuation for financing. They can differ, and sellers who assume the assessment supports their price often get surprised.

What is a realistic gap to plan for? In a market with strong appreciation, budget for a possible gap of 3% to 8% between expectation and appraisal. In a declining market, plan for more and keep a cash cushion so a low number does not stall your refinance.

The finished value is decided long before the appraiser arrives. It is decided by the lot you pick and the rents you can actually earn. Test your lot’s economics in about two minutes before you build to a number that may not hold.

David Babakaiff, Co-Founder, VanPlex | PlexRank™ | Profit with Multiplex
Frequently asked questions

Why did my finished multiplex appraise lower than expected?

A completed rental multiplex is valued mostly through the income approach, which takes the net operating income the building produces and divides it by a market cap rate. If actual rents come in below what was projected, or operating costs run higher than planned, net operating income drops and the appraised value drops with it, because a small miss on monthly rent per unit gets multiplied across every unit and then divided by a small cap rate, which magnifies the effect.

What are the three ways an appraiser can value a multiplex?

An appraiser has three tools. The sales comparison approach looks at recent sales of similar properties and adjusts for differences. The income approach takes the net operating income the building produces and divides it by a market cap rate. The cost approach adds land value to the cost of rebuilding the structure, then subtracts depreciation. For a completed rental multiplex, market participants price on the income it produces, so the income approach usually leads and sales comparison acts as a check.

Why did my multiplex appraise lower than my single-family neighbour's house?

The two properties use different valuation methods. A neighbouring single-family house is valued mainly through comparable house sales nearby, since there are plenty of similar houses to compare against. A completed rental multiplex is valued mainly through the income it produces. If that income is soft, the multiplex value comes in soft regardless of what nearby houses are selling for.

How does a low appraisal affect my construction loan?

A lender sizes the mortgage off the appraised value, up to whatever loan-to-value ratio the lending program allows, not off the purchase price or the construction cost spent. If the appraisal comes in low, the loan comes in low, and the borrower has to cover the difference in cash. This becomes a real problem for anyone counting on the finished appraisal to refinance out of a construction loan.

Can I challenge a low multiplex appraisal?

Sometimes. If the appraiser used weak comparables or missed real rent data, the owner can provide better evidence to support a higher figure. A genuine income shortfall cannot be argued away, though. Fixing the underlying number usually means fixing the rents or the construction cost, which is difficult to do after the building is already finished.

Does BC Assessment value match a lender's appraised value for a multiplex?

No. BC Assessment produces a mass-appraisal figure used for property tax purposes, while a lender's appraisal is a specific market valuation done for financing. The two figures can differ, and sellers who assume the BC Assessment value supports their asking price often get surprised when the lender's appraisal comes back lower.

What size appraisal gap should I budget for on a multiplex project?

In a market with strong appreciation, budget for a possible gap of 3% to 8% between the expected value and the appraised value. In a declining market, plan for a larger gap and keep a cash cushion, so a low appraisal number does not stall the refinance out of the construction loan.

Why do rising construction costs make the cost approach less useful for new multiplex builds?

Multifamily construction costs are more than 30% above where they sat five years earlier. When it costs far more per square foot to build a new multiplex than to buy a functionally similar existing building at a lower price per square foot, ground-up development starts to look irrational on paper, because the cost approach shows a wide gap between build cost and finished value that the project has to close through strong rents and a well-chosen lot.

Free 12-page guide for Vancouver-area homeowners. Build, sell, hold, or partner — side-by-side comparison of the numbers, timeline, and risk on each path.

Verified phone required. We'll text you the link in 60 seconds.

David Babakaiff

David Babakaiff

Co-Founder, VanPlex | 25+ Years BC Construction

David Babakaiff is Co-Founder of VanPlex with 25+ years scaling BC construction. He led Alair Homes Vancouver to the 2024 HAVAN Award for Best Multiplex Unit in the GVRD. VanPlex’s PlexRank™ algorithm scores residential parcels across BC for multiplex conversion potential under Bill 44.

Want insights like this delivered weekly?

Join 2,500+ property owners getting ROI case studies, market data, and exclusive opportunities.

No spam. Unsubscribe anytime.